Mainstream Online Web Portal
LoginInvestors can view their accounts online via a secure web portal. After registering, you can access your account balances, periodical statements, tax statements, transaction histories and distribution statements / details.
Advisers will also have access to view their clients’ accounts online via the secure web portal.

The Point
Quick, actionable insights for investors


May 29
The headlines driving Aussie equities | Falling USD should lift EMs | Where to find opportunities in theme-driven markets
Loading posts...
Elise McKay: The headlines driving Aussie equities this week
Quick view
Elise McKay: The headlines driving Aussie equities this week
Here are the main factors driving the ASX this week, according to Aussie equities analyst and portfolio manager ELISE MCKAY and reported by head investment specialist CHRIS ADAMS
Read Pendal’s latest weekly equities overview.
Crispin Murray: Where to find ASX opportunities amid ‘theme-driven’ market noise
Quick view
Crispin Murray: Where to find ASX opportunities amid ‘theme-driven’ market noise
Share prices are increasingly moved by popular themes like AI disruption, trade wars, and tariff fears – without regard to company fundamentals or long-term valuations.
As a result, quality Australian companies with sound outlooks and predictable cash flows are being indiscriminately sold off.
That’s creating opportunities for active fund managers, Pendal’s head of equities Crispin Murray told Morningstar’s 2025 investment conference in Sydney last week.
“We believe this is creating more distortions in the market. It means the amplitude of mispricing is greater, and it lasts longer.”
Global market dislocation means the ASX has a range of industrial companies with predictable cash flows and returns that have been sold down and offer opportunities for investors, he says.
“One example is CSL – one of Australia’s largest, most successful companies. Five years ago it was running high – at an over-40 multiple. It’s now down to about 22 times earnings,” he says.
Fears of the impact of tariffs on CSL are misplaced, assuming the company doesn’t do anything to respond – “and I think that’s where the market’s overreacting,” argues Crispin.
“We think the risk on the tariff front is being overstated, and that’s what’s providing you the opportunity.” Pendal owns CSL.
Read more
‘Emerging markets crisis’? That’s a wildly overstated view, say our experts
Quick view
‘Emerging markets crisis’? That’s a wildly overstated view, say our experts
Some analysts have described a pattern of a weaker dollar and rising bond yields in the US as a ‘classic emerging markets crisis’.
“As veterans of actual emerging crises dating back to 1994, we consider that view to be wildly overstated,” writes Pendal’s EM team in their latest analysis.
In spite of volatility and weakness in core US financial markets, the currencies of almost all emerging markets strengthened against the US dollar in March and April. Meanwhile bond yields fell for the majority of major EMs.
“Emerging markets are driven by two major global drivers: international capital flows and international trade.
“A weaker dollar represents capital flowing out of the US and into the rest of the world – and a weaker dollar has consistently been positive for emerging markets over the past 30 years.
“Although evolving tariff policies threaten a downturn in global trade, the message from financial markets is that investor uncertainty about US economic policies is a clear positive for emerging economies and for investors in emerging markets.”
Read more
Amy Xie Patrick: China, the US, and the value of uncertainty
Quick view
Amy Xie Patrick: China, the US, and the value of uncertainty
This month’s divergence in US and China rates policies wasn’t just a curiosity for money managers, observes Pendal’s head of income strategies, Amy Xie Patrick.
“It’s a study in contrasts, a reflection of deeper structural differences, and a reminder that policy effectiveness doesn’t always come wrapped in transparency or even democracy,” says Amy in her latest markets analysis.
On May 7, the US Fed left rates unchanged despite growing political pressure. Meanwhile, the People’s Bank of China delivered another dose of stimulus.
“One central bank faced market criticism over its non-committal guidance,” notes Amy. “The other moved swiftly and silently, without needing to justify its decision.
“Perhaps the most contrarian yet valuable takeaway is that less policy guidance may be a good thing.
“By avoiding the hard task of forecasting far into the future, we free ourselves from unhelpful narratives may that turn out to be false.
“By focusing on getting it right rather than always being right, we’re able to preserve the flexibility to change course when the fundamentals change.”
Read Amy’s full article here
Latest updates from our fund managers

Income and Fixed Interest
Tim Hext: Australia to expect state budget downgrades
June 25, 2025
See all
Emerging Markets
Emerging markets: Look past commodity exports to countries with strong domestic demand
July 26, 2023
See allSubscribe to The Point
Get regular insights on investing, market analysis and portfolio management from the experts at Perpetual Group.
Follow
The Point

These podcasts are for general information purposes only, should not be considered as a comprehensive statement on any matter and should not be relied upon as such. They have been prepared without taking into account any recipient’s personal objectives, financial situation or needs. Because of this, recipients should, before acting on the information, consider its appropriateness having regard to their or their clients’ individual objectives, financial situation and needs. The information is not to be regarded as a securities recommendation.
The information in these podcasts may contain material provided by third parties, is given in good faith and has been derived from sources believed to be accurate as at its issue date. While such material is published with necessary permission, and while all reasonable care has been taken to ensure that the information in this presentation is complete and correct, to the maximum extent permitted by law neither Pendal nor any company in the Pendal group accepts any responsibility or liability for the accuracy or completeness of this information.
Any projections contained in these podcasts are predictive and should not be relied upon when making an investment decision or recommendation. Whilst we have used every effort to ensure that the assumptions on which the projections are based are reasonable, the projections may be based on incorrect assumptions or may not take into account known or unknown risks and uncertainties. The actual results may differ materially from these projections.
Performance figures are calculated in accordance with the Financial Services Council (FSC) standards. Performance data (post-fee) assumes reinvestment of distributions and is calculated using exit prices, net of management costs. Performance data (pre-fee) is calculated by adding back management costs to the post-fee performance. Past performance is not a reliable indicator of future performance.
For more information, please call Customer Relations on 1300 346 821 8.00am to 6:00pm (Sydney time) or visit our website www.pendalgroup.com
Global equities: The more AI grows, the smaller the market could be
Not surprisingly, artificial intelligence was one of the big themes in the latest US quarterly reporting.
In Asia there’s a similar level of market excitement, with Taiwanese chipmaker TSMC up 20 per cent this year for example.
But it’s divorced from reality, reckons Pendal Asian Shares PM Samir Mehta.
At TSMC, AI accounts for just 6 per cent of revenue, with the balance of sales coming from stagnant laptop and phone markets, he says.
And the technology’s very success could curtail demand, he cautions.
Enthusiastic long-term AI industry revenue forecasts are often based on growing uptake of per-user licences.
But if AI succeeds in its promise of making business more productive, companies will reduce staffing.
“The effect of raising productivity is going to mean fewer people will need that software because fewer people are employed,” Samir says.
ASX midcaps: Unearthing the potential of mineral sands
Quick view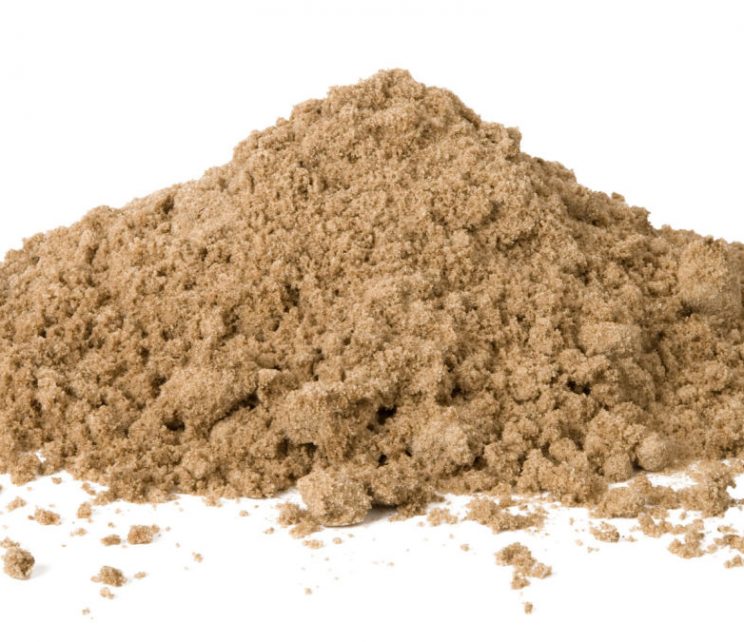
ASX midcaps: Unearthing the potential of mineral sands
Whether rubbing sunscreen on your face, reloading your printer ink or painting a wall at home, you’re probably consuming mineral sands.
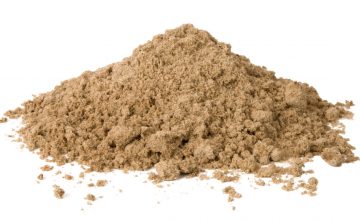
Mineral sands are old beach, river or dune sands that contain concentrations of rutile, ilmenite, zircon and monazite.
They have a variety of uses from paint and paper through to toothpaste, sun cream and ceramics – and the biggest mineral sands producer in Australia is ASX-listed Iluka Resources.
Iluka is a holding in Pendal Midcaps Fund, which focuses on the 100 biggest companies outside the ASX50 – a good hunting ground for fast-growing sectors such mineral sands and rare earths.
“Mineral sands is a steady business that Iluka has grown up doing, says Pendal equities analyst Jack Gabb.
Iluka is now building a rare earths refinery in Western Australia which would process minerals such as neodymium and dysprosium for use in electric vehicles and clean-energy generation.
There’s opportunity in China stocks if you know where to look
Quick view
There’s opportunity in China stocks if you know where to look
China’s uncertain economic outlook presents an opportunity for discerning equities investors, argues Pendal’s Asian Share Fund manager, Samir Mehta.
“The Chinese stock markets were doing quite well until about January-February but have now handed back almost all of their returns this year,” says Samir.
“Over the next few years, maybe even a decade or more, we should expect China’s GDP growth to be significantly lower than in the past.
Still, Samir believes it’s a good time to look for Chinese companies with robust market positions and strong cash flows.
“Companies in sectors with concentrated market share positions, or where they possess pricing power and – better still – where there is a focus on cutting costs and generating cash flows without affecting growth.”
Samir names Tencent Music (the Spotify of China) and gaming giant Netease as standouts among others.
Mid-caps: Re-energised lithium price could power up ASX producers
Quick view
Mid-caps: Re-energised lithium price could power up ASX producers
Lithium prices made a sharp comeback in May after steep falls this year.
That could be good news for battery metal stocks, which are commonly found among ASX midcaps.
The price rebound – about 80% in May – should persist in coming months as an oversupply in key Chinese markets dissipates, believes Pendal’s Brenton Saunders.
“The falling lithium price was largely due to quite a significant de-stocking in China – principally in the battery part of the lithium value chain, which seems pretty close to clearing now,” says Brenton, who manages Pendal MidCaps Fund.
“That’s being driven by a step-up in demand for electric vehicles again, partly due to extended subsidies and incentive support from China’s government.”
The result is a more balanced supply chain of batteries and battery precursor materials, which has allowed prices for lithium to start to rise again.
“We expected this to happen, but it’s possibly coming through a little bit earlier than expected.”
Midcap case study: Lithium producer Allkem is well positioned for a rebound in lithium prices
Quick view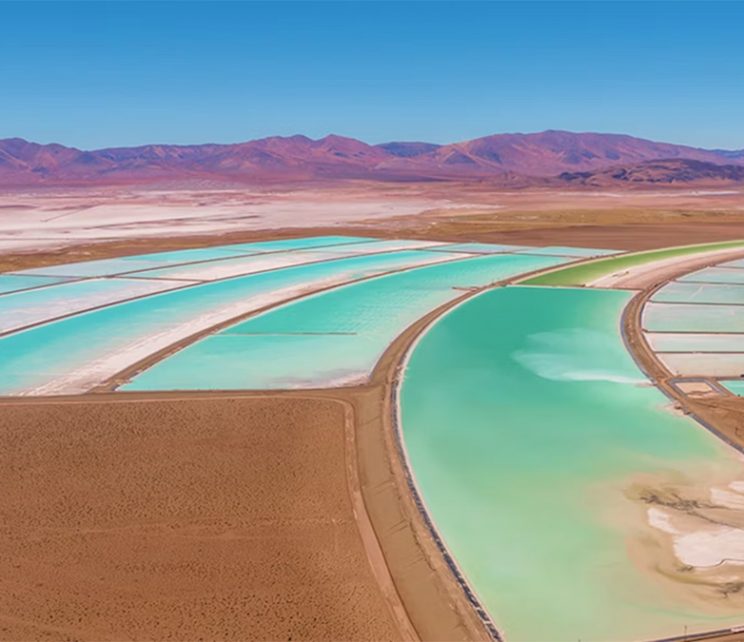
Midcap case study: Lithium producer Allkem is well positioned for a rebound in lithium prices
Among Australian mid-cap stocks, few companies get more media attention than lithium producers.
And as last week’s announced merger of ASX-listed Allkem and New York-listed Livent shows, they’re getting plenty of corporate attention as well.
What does the mooted $16 billion merger tell us about the lithium market, particularly in the wake of a price fall since late last year?
“Our view is that there is a rebound coming in lithium prices,” argues Pendal investment analyst Jack Gabb, citing higher demand for electric cars and an end to destocking in China.
Pendal holds Allkem shares in Pendal Midcap Fund and Pendal Horizon Fund.
One of Allkem’s advantages is its diversification of products, says Jack.
“It’s majority lithium carbonate but also has exposure to spodumene and lithium hydroxide. That’s all three lithium products while other producers are picking one or two.”
Global equities: What investors are missing about south-east Asian banks
Quick view
Global equities: What investors are missing about south-east Asian banks
Global equities investors might be wary of US and European bank stocks right now.
But this year’s slow-burn banking crisis in the West – which has seen the collapse of three US banks and the demise of Credit Suisse – has so far left Asian banks relatively unscathed, points out Pendal’s Samir Mehta.
Resilience among Southeast Asian banks indicates a growing maturity among regulators and governments in the region that may be missed by investors, says Mehta, who manages Pendal Asian Share Fund.
Experienced investors will recall Southeast Asia’s currencies, markets and banking systems were heavily impacted in the 1997 crisis and GFC.
But the environment for banks has improved in Singapore, Indonesia, Malaysia and even Thailand, says Samir.
Brenton Saunders: ASX mid-caps offer exposure to fast-growing sectors such as battery metals
Quick view
Brenton Saunders: ASX mid-caps offer exposure to fast-growing sectors such as battery metals
Australia finally has a national strategy to “encourage greater use of cleaner, cheaper-to-run electric vehicles”.
The new ALP policy, alongside similar plans around the world, should help boost demand for “battery metals” such as lithium, produced by a range of ASX-listed miners.
What’s the best way to get exposure to quality stocks in this sector?
Pendal PM Brenton Saunders argues in favour of Aussie mid-cap portfolios.
Mid-cap portfolios are typically less concentrated and offer access to fast-growing industries such as cloud computing, medical innovation and battery metals.
Medium-sized companies tend to offer higher earnings growth than large-cap companies, often with less risk than small caps, says Brenton.
Brenton manages Pendal MidCap Fund, which invests in the 100 biggest companies outside the ASX50, with market caps ranging from around $1 billion to $10 billion.
“It’s really the sweet spot of corporate Australia. It’s a very useful addition to any balanced portfolio.”
Brenton and Australian lithium industry pioneer Ken Brinsden explained the opportunities in a recent webinar.
Aussie equities: What we can expect from earnings in the second half
Quick view
Aussie equities: What we can expect from earnings in the second half
Australia’s economic cycle has gone on longer than expected – and it showed in the recently ended ASX earnings season.
Somewhat surprisingly, most parts of the economy are still in reasonably good shape despite a string of interest rate rises.
The strong jobs market is a factor, helping prop up consumer spending.
“But the expectation is that higher interest rates will likely hurt earnings in the rest of the financial year,” says Brenton Saunders, who manages Pendal MidCap Fund.
“Across the market as a whole, revenue beats were pretty widespread even though many companies missed earnings forecasts at the bottom line. Revenue beats were much higher than profit beats.
“We saw profit margins reduce and that relates to higher costs. In many cases, despite high product price increases, costs increased at a faster rate, resulting in margin pressure.”
Loading posts...
Subscribe to The Point
Get regular insights on investing, market analysis and portfolio management from the experts at Perpetual Group.